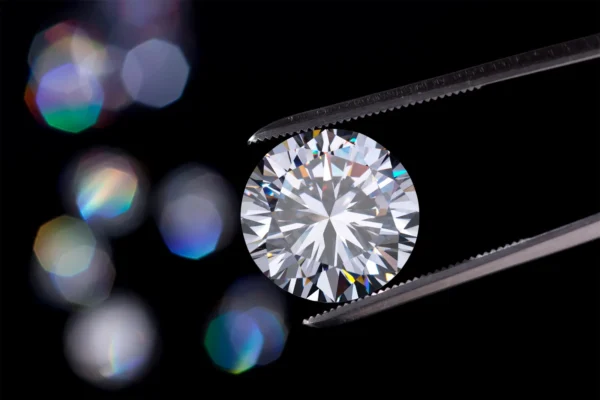
Zimbabwe earned US$62.3 million from diamond exports between January and September 2026, selling 2.52 million carats at an average of approximately US$24.72 per carat, as falling realised values continue to weigh on the sector despite efforts to increase production and improve processing, Mining Zimbabwe can report.
By Rudairo Mapuranga
The figures highlight a widening gap between the volume of diamonds reaching the market and the revenue generated from them, placing greater emphasis on product quality, recovery efficiency and the economics of Zimbabwe’s predominantly alluvial diamond resources.
The decline is particularly significant when compared with the country’s recent export performance. Zimbabwe exported 5.59 million carats worth US$297.38 million in 2023, equivalent to US$53.18 per carat. In 2024, exports increased to 7.77 million carats, but earnings fell to US$234.39 million, with the average value declining to US$30.16 per carat.
The deterioration continued in 2025, when Zimbabwe exported 4.61 million carats valued at approximately US$125.18 million, yielding US$27.16 per carat, according to Kimberley Process data.
Between 2023 and 2025, export volumes declined by approximately 17.6%, while earnings fell by nearly 58%. The average export value per carat dropped by about 49%, indicating that the revenue decline has been considerably sharper than the reduction in volumes.
The figures suggest that Zimbabwe’s diamond challenge extends beyond the quantity of stones mined or sold. The value of the product reaching the market, alongside prevailing rough-diamond prices and the composition of sales, has become central to the sector’s financial performance.
Export Earnings Expose the Value Problem
The weakness persisted in 2026. Diamond exports generated US$45.7 million between January and July, compared with US$85.6 million during the same period in 2025, a decline of approximately 46.6%. The seven-month figure was also about 82.9% below the US$267.5 million recorded between January and July 2023.
By the end of September, cumulative earnings had reached US$62.3 million from 2.52 million carats sold. The resulting average of US$24.72 per carat was below the US$27.16 recorded for the whole of 2025.
These figures point to continued pressure on realised export values, although the year-to-date average should not be interpreted as a like-for-like comparison with full-year prices without accounting for differences in the mix and timing of sales.
The first quarter of 2026 had already illustrated the pressure. Zimbabwe sold 784,764 carats for US$21.55 million, giving an average of approximately US$27.46 per carat. The reported year-on-year declines of 11% in volume and 29% in value indicated that revenue was falling faster than the number of carats sold.
The wider production outlook has also been challenging. Reported diamond output fell from 0.44 million carats in the first quarter of 2026 to 0.35 million carats in the second quarter, a sequential decline of approximately 20.6%. The reported second-quarter figure was also substantially below the 2.03 million carats recorded in the corresponding period of 2025, although the production series and reporting basis require confirmation before the comparison can be treated as definitive.
Zimbabwe Consolidated Diamond Company (ZCDC) has set a target of five million carats for 2026, up from 3.8 million carats in 2025. Achieving that target would represent an increase of about 31.6%, but higher output alone will not guarantee a corresponding improvement in export earnings if the additional production attracts similarly weak prices.
For the sector, the commercial question is increasingly whether additional carats can be recovered and sold at a price that justifies the cost of extracting and processing them.
Marange’s Mineral Characteristics Weigh on Value
Zimbabwe’s diamond pricing challenge reflects both conditions in the international rough-diamond market and the characteristics of its own production.
ZCDC has previously identified geological constraints, product profile, geopolitical tensions, synthetic diamonds, market behaviour and the sales framework among the factors affecting its performance. The relative contribution of each factor is difficult to quantify without comparable price and quality data, but the distinction between global market weakness and the characteristics of Zimbabwean stones is important.
Much of Zimbabwe’s production comes from the Marange alluvial deposits, where diamonds are recovered from unconsolidated sediments rather than directly from primary kimberlite rock.
The product mix includes industrial-grade stones, commonly referred to as boart, which generally command lower prices than gem-quality diamonds. ZCDC has previously reported that approximately 85% to 90% of its production comprises boart diamonds. The precise proportion in current production would need to be established through updated grading data.
Marange diamonds are also associated with brown surface coatings that can obscure the stones’ appearance and affect their marketability. Where the coating can be removed without damaging the diamond, treatment may improve its appearance and potentially its realised value.
However, de-coating does not automatically transform an industrial-grade stone into a gem-quality diamond. Intrinsic characteristics, including clarity, colour, size and structural integrity, continue to determine the commercial value of each stone.
The distinction matters because the sector cannot rely on cleaning technology alone to overcome the limitations of its product mix. The commercial benefit will depend on how much saleable quality improves, the proportion of stones responding to treatment and whether buyers pay a premium for the processed product.
Global Market Weakness Compounds the Challenge
Zimbabwe’s difficulties have unfolded during a sustained downturn in the natural rough-diamond market, with weaker jewellery demand, excess inventory and competition from laboratory-grown diamonds contributing to pressure on prices.
Laboratory-grown diamonds have changed consumer price expectations, particularly in segments where buyers are more sensitive to price than to the distinction between natural and synthetic stones. Their impact on rough-diamond demand, however, varies by market segment and should not be treated as the sole explanation for Zimbabwe’s declining export receipts.
The weakness has also affected major international producers. De Beers reported lower average realised prices during the first half of 2026, illustrating the extent to which the downturn has affected even established suppliers.
Comparisons with large producers nevertheless require caution. Their average prices reflect different mixes of gem, near-gem and industrial stones, as well as differences in size distribution, sorting and sales arrangements. Zimbabwe’s average export value cannot be compared directly with a producer’s realised price without accounting for these differences.
For Zimbabwe, the combination of weaker international prices and a production mix weighted towards lower-value stones leaves limited room to compensate for falling unit prices simply by increasing volumes.
De-Coating Technology Targets a Specific Weakness
ZCDC has begun a value-addition programme aimed at improving the marketability of diamonds recovered from Chiadzwa.
In August 2026, the company confirmed that it had started value-addition work in June after acquiring specialised de-coating equipment from India. The programme forms part of efforts to improve the value of diamonds before export.
The treatment targets surface coatings that can obscure the appearance of stones. Its potential commercial benefit lies in enabling buyers to assess the underlying characteristics more clearly and, where the treatment improves marketability, potentially offer better prices.
The next measure of success will be the difference between the realised prices of treated and untreated stones, taking account of their original quality and size. Without that comparison, improved appearance alone would not establish the financial return on the investment.
The programme also raises operational questions, including treatment costs, processing throughput, the proportion of stones suitable for de-coating and whether the technology can be applied economically at scale.
These considerations are important in a low-value product environment, where additional processing expenditure must be justified by a measurable improvement in recovery or sales revenue.
XRT and Plant Expansion Could Improve Recovery Economics
Alongside de-coating, ZCDC has pursued processing improvements intended to increase diamond recovery and reduce operating costs.
The proposed A700 Phase 3 plant expansion is intended to improve processing capacity and recovery across the ore body, while greater use of X-ray transmission (XRT) technology is expected to support diamond concentration and recovery.
XRT systems identify differences in the way materials absorb X-rays, allowing suitable processing equipment to separate diamond-bearing material from waste based on measurable characteristics. Their effectiveness depends on factors such as feed preparation, particle size, sensor performance, plant configuration and the characteristics of the material being treated.
Improved recovery can increase the proportion of diamonds recovered from mined ore, reducing the number of valuable stones lost during processing. However, the benefit depends on the additional carats recovered, their quality and value, and the capital and operating costs required to obtain them.
The proposed consolidation of processing operations within a single footprint is also intended to reduce ore-haulage costs. If implemented successfully, shorter or more efficient material-handling routes could lower unit costs and improve plant utilisation.
The critical indicators will be recovery rates, throughput, downtime, processing costs per tonne and the value of additional diamonds recovered. These measures will show whether the investment improves the economics of production rather than merely increasing installed capacity.
ZCDC has also reserved 10% of its production for the local market and previously worked with Aurex Diamonds Operations in Harare on cutting and polishing selected stones. Domestic beneficiation offers a route to retain more value within Zimbabwe, although its contribution will depend on the quality and quantity of stones suitable for cutting and polishing, as well as the competitiveness of local processing costs and access to buyers.
Kimberlite Exploration Offers a Longer-Term Option
A further part of ZCDC’s strategy is the acceleration of kimberlite exploration with Russian diamond producer Alrosa.
The distinction between alluvial and kimberlite deposits is important for long-term mine planning. Alluvial operations recover diamonds that have been eroded from their original host rocks and deposited in sediments. Kimberlite operations target the primary rock in which diamonds occur.
A successful kimberlite discovery could diversify Zimbabwe’s resource base and create opportunities for a different production profile. However, kimberlite deposits vary widely in diamond grade, stone quality, size distribution and economic viability. Their value cannot be assumed from the deposit type alone.
Exploration must establish the presence and continuity of mineralisation, diamond content, recoverable grade and the characteristics of the stones. Further work is then required to determine whether a deposit can support commercially viable mining and processing.
The transition from alluvial production towards primary deposits would therefore be a long-term resource-development strategy rather than an immediate solution to falling export earnings.
Its significance will depend on exploration results, the scale of any discoveries, development costs and the quality of diamonds ultimately recovered.
Fiscal Pressures and Investment Requirements
ZCDC has also sought changes to the fiscal framework governing diamond production.
Among the proposals reported by the company are a reduction in diamond royalties to 5%, an increase in foreign-currency retention on export sales from 70% to 80%, and the formal removal of a 2.5% depletion fee that it says remains on its books without a confirming statutory instrument.
The company has argued that changes to these arrangements would help it manage costs and retain more resources for investment at prevailing prices. These remain proposals and should not be confused with approved changes to the fiscal regime.
ZCDC has also identified a proposed US$7.2 million capital injection in connection with its transition towards an owner-mining model, which is intended to reduce reliance on contracted mining services.
The economic case for that transition will depend on the capital required to acquire and maintain equipment, workforce and maintenance capacity, fuel and other operating costs, and the productivity achieved compared with contracted mining.
In a low-price environment, changes that reduce unit costs can be as important as improvements in realised prices. However, lower royalties or higher foreign-currency retention do not, on their own, resolve the underlying problem of low-value production. Their impact depends on whether the additional cash retained is sufficient to support more efficient operations and commercially justified investment.
Measuring Whether the Recovery Is Real
Zimbabwe’s diamond sector faces two connected challenges: a difficult international market and the need to improve the value obtained from its own resources.
The export figures demonstrate the scale of the pressure. Between 2023 and 2025, the average value per carat fell from US$53.18 to US$27.16, while annual export earnings declined from US$297.38 million to about US$125.18 million. By September 2026, the reported year-to-date average had fallen further to approximately US$24.72 per carat.
The response will need to be judged by more than production targets. De-coating must demonstrate a measurable price benefit; plant upgrades must improve recovery and reduce unit costs; beneficiation must generate commercially sustainable returns; and kimberlite exploration must deliver economically viable resources before it can materially alter the country’s production profile.
The distinction between output and value is central. More carats can support higher revenue when prices and product quality justify the additional costs, but production growth alone cannot guarantee a recovery in earnings.
For Zimbabwe, the decisive test will be whether mining and processing improvements can raise the value realised from each carat while keeping the cost of recovering and marketing it under control. Until that happens, the country risks increasing physical output without achieving a commensurate improvement in the financial contribution of its diamond resources.