Home Blog Page 9

A Day’s Wage, No Security: The Precarious Reality of Casual Workers in Mhangura

0

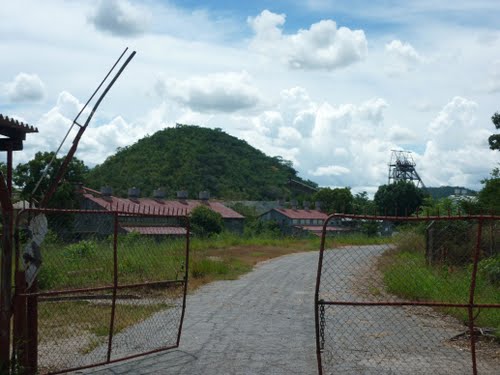
In the shadow of the former Mhangura Copper Mine, a new mining operation is processing copper-bearing material from dumps and tailings that have remained part of the area’s mining landscape for decades, Mining Zimbabwe can report.

By Rudairo Mapuranga

For some young men working at the operation, however, the revival of mining activity has come with little certainty about what tomorrow will bring.

Four workers from the Mhangura area told this reporter that they are called in when their labour is required, paid according to the hours they work and have not been given written employment contracts.

“They just call us. We don’t have a contract. We are four, and they give us a dollar per hour,” one of the workers said on condition of anonymity.

The workers said they perform different duties at the operation, including work around the ball mills and other sections of the processing plant. On busier days, they said, the number of people engaged for similar work can increase.

Their accounts point to an employment arrangement in which work is dependent on the operational needs of the day, leaving workers uncertain about when they will next be called in.

For young people in Mhangura, a town whose economy was severely affected by the closure of the former copper mine, the availability of work remains a critical issue.

Questions over employment arrangements

The operation, commonly referred to locally as East Asia Mine, is linked to Chinese investor Zhijiu Mining and the Zimbabwe Mining Development Corporation (ZMDC).

The project processes material associated with historical copper mining activities in Mhangura. Previous official statements have indicated that the operation is expected to create employment and contribute to the revival of economic activity in the former mining town.

ZMDC Managing Director Blessed Chitambira has previously stated that the operation employs about 100 people.

However, the accounts provided by the four workers raise questions about how workers engaged on casual or as-needed arrangements are classified and whether they are included in the company’s stated employment figures.

The workers said they are paid US$1 per hour and are contacted when their labour is needed.

Mining Zimbabwe sent questions to ZMDC General Manager Blessing Chitambira seeking clarification on the employment status of workers engaged in this manner, including whether they are formally contracted, what protections apply to them and whether such workers are included in the operation’s employment figures.

At the time of publication, no response had been received despite the questions having been sent more than a month earlier.

Local employment concerns

The workers who spoke to this reporter said many of the people engaged at the operation come from the Mhangura area. However, they also said some workers have come from Harare and Bindura, including individuals performing work that, according to the workers, does not necessarily require specialised professional qualifications.

This has raised questions among some local residents and workers about the extent to which employment opportunities are being prioritised for people from the host community.

The issue is particularly significant in Mhangura, where the closure of the original copper mine left a lasting economic impact.

The former Mhangura Copper Mine shut down in 2000, bringing an end to decades of mining activity that had supported the town and surrounding communities. Thousands of people were affected directly and indirectly by the closure, and the town has struggled to recover economically.

The return of mining activity therefore brought expectations of employment and renewed economic opportunities.

For casual workers, however, access to work does not necessarily translate into employment security.

A gap between policy and practice

The experiences described by the workers reflect broader concerns raised by organisations advocating for greater accountability in Zimbabwe’s extractive sector.

The #PayTheHarm Media Documentation Exercise seeks to document the social, health, environmental and economic impacts experienced by communities affected by mineral extraction, while strengthening public discussion around accountability and responsible mining.

ActionAid Zimbabwe Country Director Dr Selina Pasirayi has previously highlighted the gap that can exist between policy commitments and implementation on the ground.

“We have strong policies on paper, but implementation is where the gap is. Without strong accountability systems, coordination and financing that reaches the ground, policy ambition will not translate into real change in communities that are supposed to benefit from these interventions.”

Her observations raise an important question for mining communities such as Mhangura: how can the benefits promised through mining investment be translated into meaningful and sustainable opportunities for the people living closest to the operations?

Employment is one of the most immediate ways in which communities expect to benefit from mining. But the quality, security and conditions of that employment are equally important.

The four workers who spoke to this reporter said they remain dependent on being called in when their labour is required.

They work when there is work available. When the day’s shift ends, they do not know when the next call will come.

An unanswered question

The revival of mining in Mhangura has brought renewed activity to a town whose identity and economy were once built around copper.

The operation has also created jobs and opportunities. But the experiences of casual workers raise questions about whether all forms of employment created by the project provide the security and certainty that communities hoped would accompany the return of mining.

The workers who spoke to this reporter are part of the daily labour required to keep sections of the processing operation running.

Yet they say they have no written contracts and are engaged only when their services are needed.

Whether such workers are formally recognised within the operation’s employment structure, what protections apply to them and how their working arrangements are regulated remain questions that ZMDC had not answered by the time of publication.

For the young men waiting for the next call from the mine, however, the issue is more immediate.

Today’s work brings today’s wages.

Tomorrow remains uncertain.

Kambamura joins global mining leaders at China Africa Mining 2026

0

TIANJIN, CHINA — September 11, 2026 — Mines and Mining Development Minister Dr (Eng) Polite Kambamura is leading Zimbabwe’s delegation at the 28th China Mining Conference and Exhibition (CHINA AFRICA MINING 2026), where governments, mining companies and investors are discussing the future of global mineral supply chains, Mining Zimbabwe can report.

Kelvin Sungiso

The conference opened on September 10 at the Tianjin Meijiang Convention and Exhibition Center and is being held under the theme “Win-win Cooperation, Green and Intelligent Development.”

Minister Kambamura is attending at the invitation of China’s Minister of Natural Resources, Guan Zhi’ou. The conference opened alongside the Ministerial Forum on International Mining Cooperation, which this year is focused on “Forging a Mutually Beneficial Mining Industrial and Supply Chain.”

The opening brought together 33 ministers and representatives from 60 countries, as well as mining executives, investors, financiers and technical experts, highlighting the growing importance of international cooperation in securing mineral supply chains.

China’s Vice Premier He Lifeng, a member of the Political Bureau of the Communist Party of China Central Committee, delivered the keynote address.

In his remarks, He highlighted China’s cooperation with mineral-rich countries and pointed to Zimbabwe as one of the examples of what such partnerships can achieve.

He specifically referenced developments in Zimbabwe’s lithium sector, citing Bikita Minerals and Prospect Lithium Zimbabwe.

The two operations have become important components of Zimbabwe’s drive to move beyond the export of unprocessed mineral concentrates and develop greater domestic value addition.

Prospect Lithium Zimbabwe, which operates the Arcadia lithium mine in Goromonzi, dispatched Zimbabwe’s first export of locally produced lithium sulphate in April 2026. Bikita Minerals, in Masvingo Province, is also developing a lithium sulphate plant as it expands its downstream processing capacity.

The developments come as Zimbabwe seeks to capture more value from its mineral resources.

Gold buying prices in Zimbabwe per gram/ ounce, 11 September 2026

0

Gold buying prices in Zimbabwe per gram/ ounce, 11 September 2026, from the official gold buyer and exporter, Fidelity Gold Refinery (FGR).

1 oz = 31.1035 g

Gold CategoryPrice (US$/g)Price (US$/oz)
SG 90% and above$130.65/g$4,063.67
SG 85% and above but below 90%$129.27/g$4,020.75
SG 80% and above but below 85%$127.89/g$3,977.82
SGF/SG 75% and above but below 80%$126.50/g$3,934.59
Sample 5g & above but below 10g$124.43/g$3,870.21
Fire Assay Cash$131.34/g$4,085.13


Note: The Fire Assay cash price applies to gold above 100g, with no sample deduction.

A sample of not more than 10g is deducted for the Fire Assay Transfer price.

#GoldPrices #GoldBuying #GoldMarket #GoldTrading #GoldRate #GoldPriceToday #GoldNews #PreciousMetals #GoldIndustry #GoldEconomy #FidelityGoldRefinery

Zimbabwe needs a more aggressive Global Campaign to win Mining Investors

0
Zimbabwe has spent years telling the world that it is rich in minerals.

It now needs to spend far more time showing the world what that opportunity looks like.

By Keith Sungiso

The country has no shortage of a mining story to tell. It’s well known that the country has more than 60 internationally tradeable minerals, including major deposits of platinum-group metals, chrome, gold, lithium coal and diamonds. Foreign investors can participate across the mining value chain, including exploration, extraction, logistics, beneficiation and technical services.

The question is not whether Zimbabwe has a mineral story.

The question is whether enough of the world’s investors are hearing it.

And that is where Zimbabwe needs to become much more aggressive.

Zimbabwe cannot market itself from home

For too long, the country’s international mining image has been shaped by what people have heard about Zimbabwe, not by what they have seen and experienced in its mining industry today.

Changing that perception will not happen through one conference, one investment forum or one delegation.

It will happen through consistent exposure. Whilst online presence is strong and consistent via industry publications like Mining Zimbabwe, Zimbabwe needs to be present wherever serious conversations about mining investment, critical minerals, exploration, technology, infrastructure and mineral processing are taking place.

If there is a credible international mining conference in Australia, Canada, Europe, Asia, the Middle East, Africa or elsewhere where investors, mining companies, financiers and technology providers are gathering, Zimbabwe should be asking a simple question:

Why aren’t we there?

ADU has demonstrated the value of this approach. At the 2026 event in Perth, Zimbabwean officials reported receiving specific enquiries from investors about commodities and how they could enter the market. Investors also raised practical questions around electricity, exploration and project development.

That is precisely what international engagement should produce, not just applause for Zimbabwe’s mineral potential, but conversations that can eventually lead to exploration, partnerships and investment.

One conference cannot change a country’s reputation

There is a temptation to treat major mining conferences as annual events on a calendar.

Zimbabwe should treat them as part of a much bigger campaign.

A delegation arrives. It makes presentations. It holds meetings. It leaves.

Then, months later, another delegation does much the same thing.

That approach is not enough.

If Zimbabwe wants to neutralise the negative perceptions that have accumulated around the country over the years, it needs to outcommunicate them.

That requires being visible again and again.

An investor who meets Zimbabwean officials in Perth should be able to encounter Zimbabwe again in London, Toronto, Cape Town, Dubai or another major mining centre.

The message should be familiar, but the conversation should become increasingly specific.

Here are the projects.

Here are the geological opportunities.

Here are the investment requirements.

Here is the infrastructure.

Here are the processing opportunities.

Here is what has changed.

And here is who you can speak to if you want to take the discussion further.

That is how perceptions change, through repeated exposure to credible information and credible people.

Zimbabwe should be everywhere the mining industry is

The world’s mining calendar is far bigger than just ADU and Mining Indaba, just to mention the familiar two.

There are conferences dedicated to gold, lithium, copper, platinum-group metals, critical minerals, exploration, mining finance, equipment, energy, infrastructure, technology and mineral processing.

Zimbabwe does not necessarily need a large pavilion at every event.

Sometimes a senior government representative, geological expert, investment official or mining executive sitting on a panel can be enough to put the country into the conversation, and government must also consider deploying officials with knowledge of mining (eg geologists, mining engineers) at all its embassies to ensure the country is ready to answer questions precisely and accurately whenever the need arises.

Sometimes a focused investment forum is more valuable than a large exhibition stand.

Sometimes the most important meeting happens away from the main stage.

The objective should not be attendance for attendance’s sake.

The objective should be to make Zimbabwe increasingly difficult to ignore.

Tell investors what they can actually invest in

The message also needs to mature.

Saying that Zimbabwe is “mineral-rich” is no longer enough.

Investors already know that.

The more important question is: What can I do in Zimbabwe?

The country needs to arrive at international conferences with clearly packaged opportunities.

A potential investor should be able to identify an exploration opportunity, a producing mine, a processing project, an infrastructure requirement or a technology opportunity and understand what is required to participate.

This is particularly important because investor conversations are becoming more commercially specific.

At ADU 2026, Zimbabwean officials said investors were approaching the delegation with specific commodity requirements and asking how they could be facilitated. The government said it was recording those interests by commodity so they could be followed up after the conference.

That is the kind of engagement Zimbabwe should build on. Zimbabwe excelled at Africa Down Under in 2026 because it did more than simply show up. The country arrived with a stronger and more coordinated presence, held dedicated investment engagements and put specific opportunities in front of investors.

Every conference should create a pipeline, not just a photograph.

The follow-up is where the real marketing begins

A conference may last three days.

An investment decision can take years.

Zimbabwe therefore needs to treat every international event as the beginning of a relationship rather than the end of a trip.

If a company expresses interest in lithium in Perth, someone should follow up.

If an exploration company asks about geological data in Toronto, someone should follow up.

If a processor wants to understand Zimbabwe’s chrome or platinum opportunities in London, someone should follow up.

If a financier wants to discuss infrastructure in Dubai, someone should follow up.

The country should know who it met, what they wanted, what information they requested and what happened next.

That may sound basic, but it can make an enormous difference.

The ultimate measure of a successful conference should not be how many people visited the Zimbabwe stand.

It should be how many serious conversations continued after everyone went home.

Zimbabwe has a stronger story to tell than it sometimes realises

The country’s mining proposition is also changing.

Zimbabwe is increasingly talking about beneficiation, value addition and industrialisation rather than simply extracting and exporting minerals.

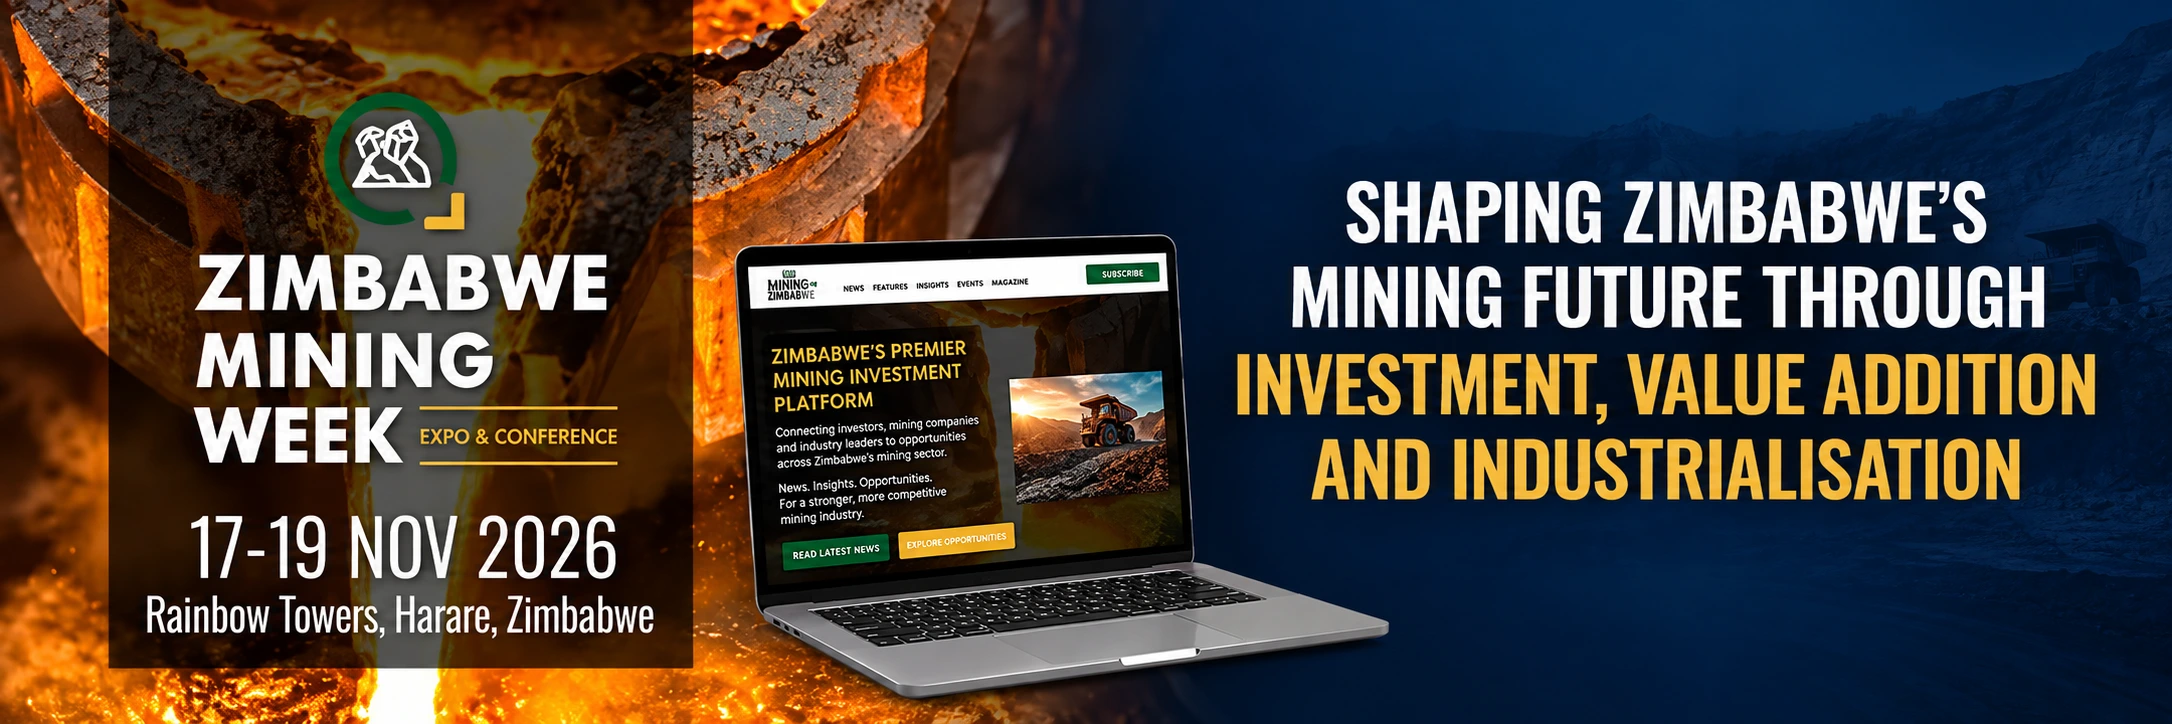
The country’s upcoming Zimbabwe Mining Week, for example, is explicitly positioning mining around investment, value addition and industrialisation, while bringing investors, government, project developers, financiers and suppliers together.

That is an important shift.

Zimbabwe can tell an investor that the opportunity is not simply to operate a mine.

Opportunities also exist in processing plants, engineering, mining equipment, energy, logistics, technology, and other services that support the mining value chain.

That makes the potential market considerably larger.

Perception changes when people see progress

Zimbabwe should not try to pretend that the country has no challenges.

That would be counterproductive.

Serious investors will ask difficult questions about regulation, infrastructure, power, foreign exchange, policy consistency and the operating environment. Current international investment guidance continues to identify concerns that investors consider when assessing Zimbabwe.

The answer should not be to avoid those questions.

It should be to meet them directly.

A confident mining jurisdiction does not need to claim that everything is perfect.

It needs to demonstrate what is improving, explain what still needs work and show investors where genuine opportunities exist.

That is a much more credible way of rebuilding confidence.

Zimbabwe needs a global mining presence

There is a bigger opportunity here.

Zimbabwe could develop a deliberate international mining-marketing programme that runs throughout the year rather than intensifying only when ADU or Mining Indaba approaches.

Government, the Zimbabwe Investment and Development Agency, the Ministry of Mines, the Geological Survey, the Chamber of Mines, Fidelity Gold Refinery (FGR), MMCZ and private-sector mining companies could work from a common international calendar.

They could identify the conferences that matter, decide which ones require government representation, which require industry participation and which require targeted investor meetings.

The country could also use its diplomatic missions more aggressively to arrange investment meetings around major mining events.

The message would become continuous.

Not:

“Zimbabwe is open for investment.”

But:

“Here are the opportunities. Here is the evidence. Here is what is changing. Come and see for yourself.”

The world needs minerals – Zimbabwe needs to be in the room

The global race for critical minerals has created an opportunity that Zimbabwe cannot afford to watch from the sidelines.

The country has significant mineral resources and an established mining industry. It also has ambitions to move further into beneficiation and value addition.

But mineral wealth does not automatically attract capital.

Investors need to know where the opportunity is, understand it and develop enough confidence to pursue it.

Zimbabwe therefore needs to market its mining sector with the same determination that companies use to market their products.

Attend the conference.

Speak on the panel.

Meet the investor.

Present the project.

Answer the difficult question.

Exchange contact details.

Follow up.

Then do it again in the next city or country.

And the next one.

Zimbabwe cannot change years of international perception overnight.

But it can change the conversation through persistent, professional and evidence-based engagement.

ADU should not be the destination. Mining Indaba should not be the destination. They should be milestones in a much bigger global campaign.

If the international mining industry is gathering somewhere to discuss minerals, investment and the future of mining, Zimbabwe should be asking to be part of that conversation.

Because if Zimbabwe wants the world to reconsider its mining potential, the country must be prepared to take its mining story to the world – repeatedly, confidently and everywhere the serious investors are.

Gold buying prices in Zimbabwe per gram/ ounce, 10 September 2026

0

Gold buying prices in Zimbabwe per gram/ ounce, 10 September 2026, from the official gold buyer and exporter, Fidelity Gold Refinery (FGR).

1 oz = 31.1035 g

Gold CategoryPrice (US$/g)Price (US$/oz)
SG 90% and above$133.34/g$4,147.34
SG 85% and above but below 90%$131.93/g$4,103.48
SG 80% and above but below 85%$130.52/g$4,059.63
SGF/SG 75% and above but below 80%$129.11/g$4,015.77
Sample 5g & above but below 10g$126.99/g$3,949.83
Fire Assay Cash$134.05/g$4,169.42


Note: The Fire Assay cash price applies to gold above 100g, with no sample deduction.

A sample of not more than 10g is deducted for the Fire Assay Transfer price.

#GoldPrices #GoldBuying #GoldMarket #GoldTrading #GoldRate #GoldPriceToday #GoldNews #PreciousMetals #GoldIndustry #GoldEconomy #FidelityGoldRefinery

Zimbabwe Turns to Hong Kong to Broaden Mining Investment Pipeline

0

Zimbabwe is seeking to widen access to international capital for mining and mineral beneficiation through a new investment cooperation agreement with Hong Kong, as the country looks to strengthen links between its mining opportunities and global investors, Mining Zimbabwe can report.

By Ryan Chigoche

The Zimbabwe Investment and Development Agency (ZIDA) and Invest Hong Kong (InvestHK), the investment promotion agency of the Hong Kong Special Administrative Region, have signed a memorandum of understanding aimed at strengthening investment flows between the two markets.

The agreement provides for cooperation on investor referrals, business missions, investment information and targeted engagements, giving Zimbabwe a framework to take investment opportunities directly to businesses and financiers operating through Hong Kong.

Mining and mineral beneficiation are among the sectors identified by ZIDA for potential investment under the partnership, alongside manufacturing, energy, agriculture and agro-processing, infrastructure and services.

For the mining industry, the significance lies in the access the arrangement could create to Hong Kong’s financial and business networks, particularly its links to mainland China. Zimbabwe can use the platform to introduce prospective investors to projects spanning mineral exploration, mining and beneficiation.

The partnership, however, does not amount to a mining investment or financing commitment. Rather, it creates an institutional mechanism for identifying potential investors, making introductions and providing information on opportunities in Zimbabwe.

That distinction places the emphasis on what happens after the agreement is signed.

ZIDA Chief Legal Officer Theresa Muchinguri said the agency wanted the partnership to result in practical connections between investors and viable projects, rather than remain an investment-promotion exercise.

“Our objective is to create stronger pathways between international investors and viable opportunities in Zimbabwe. Through this cooperation with InvestHK, we can share opportunities more directly, facilitate introductions and support businesses that are considering Zimbabwe as an investment destination,” Muchinguri said.

For mining, where projects can require substantial capital and long development periods, those connections could be particularly important. Beyond financing, international partnerships can bring technology, technical expertise and access to wider markets as Zimbabwe seeks to move further into mineral beneficiation.

InvestHK Director-General of Investment Promotion Alpha Lau said Hong Kong was well placed to facilitate those connections, describing the territory as a gateway linking Africa with Asia through its financial markets, professional services and proximity to mainland China.

“Zimbabwe is an important partner as Hong Kong deepens its engagement with Africa and the Global South under the Belt and Road Initiative,” Lau said.

The relationship is also intended to work in the opposite direction, with InvestHK expected to help Zimbabwean businesses seeking to expand into Asian markets.

The next step will therefore be turning the framework into actual investor activity. The two agencies are expected to exchange priority investment opportunities and market information, identify and refer prospective investors, and organise business missions and targeted engagements.

For Zimbabwe’s mining sector, the test will be whether those engagements ultimately translate into capital flowing into exploration, mine development and processing projects.

That comes as the country seeks to attract more investment into its mineral sector while increasing the amount of value captured locally through beneficiation.

The ZIDA-InvestHK agreement does not guarantee investment into mining, but it gives Zimbabwe another institutional route to international investors and financiers and potentially a new channel for moving its mining pipeline from the investment pitch to actual projects on the ground.

Zimbabwe platinum output hits quarterly record as global market swings to surplus

0

Zimbabwe’s refined platinum production rose to a quarterly record in the second quarter of 2026, helping offset weaker output from Russia and North America even as the global platinum market swung sharply into surplus amid a broad decline in demand, Mining Zimbabwe can report.

By Ryan Chigoche

According to the World Platinum Investment Council’s (WPIC) latest Platinum Market Review, Zimbabwean refined production increased 11% year-on-year to 152,000 ounces in the three months to June, its highest quarterly level on record.

The increase contributed to a 2% year-on-year rise in global refined mine supply to 1.47 million ounces, with higher production from South Africa and Zimbabwe more than offsetting declines in Russia and North America.

However, the stronger supply backdrop came against a significantly weaker demand environment.

The global platinum market recorded a 244,000-ounce surplus in the second quarter, compared with a deficit of about 76,000 ounces in the same period of 2025.

Total supply was broadly stable year-on-year at 1.91 million ounces, while total demand fell 16% to 1.66 million ounces.

The decline was driven by weaker automotive and jewellery demand, investment outflows and a sharp reduction in platinum bar and coin investment.

Precious-metals investment sentiment weakened during the quarter as prices corrected from earlier highs, resulting in substantial exchange-traded fund liquidations and further reducing physical platinum investment.

The market also faced a persistent macroeconomic and geopolitical overhang, with disruption associated with the Middle East conflict affecting energy, refining and petrochemical markets, while elevated energy costs reinforced inflation concerns and contributed to a more restrictive interest-rate environment.

For Zimbabwe, however, the second-quarter figures marked a strong rebound after operational disruption earlier in the year.

The increase in refined production was principally driven by a one-off drawdown of 29,000 ounces of semi-finished platinum inventory at Zimplats.

The inventory had accumulated following smelter maintenance in the first quarter.

Following the restart of its furnace in March, Zimbabwe’s platinum smelter output increased 14% year-on-year, helping the country restore production after the disruption.

Unki also recorded higher refined output during the quarter, while Mimosa’s production was affected by intermittent power disruptions.

The contrasting performance across Zimbabwe’s three major platinum operations highlights the operational factors still shaping the country’s PGM output, particularly smelter availability and electricity reliability.

Despite the record quarterly production, WPIC expects Zimbabwe’s full-year platinum production to decline 1% to 508,000 ounces.

The forecast is principally linked to lower grades at Unki, while the supply volatility experienced during the first half of the year as a result of furnace maintenance at Zimplats is expected to ease during the second half.

The projected decline comes despite an improved price environment for platinum-group metals.

Although PGM prices fell quarter-on-quarter during Q2’26, they remained significantly higher than a year earlier.

WPIC said the stronger price environment has materially improved mining economics and alleviated some of the downside risks previously associated with margin pressure.

The improvement has also encouraged some producers to restart projects that had been deferred during the previous period of weaker PGM prices, although WPIC does not expect additional supply from those projects to be realised in 2026.

Zimbabwe’s production outlook therefore sits within a broader global supply picture that remains relatively constrained.

South Africa recorded a 4% year-on-year increase in refined mine production to 1.08 million ounces during the second quarter.

The increase was primarily driven by higher refined output from Valterra Platinum, while Northam and Implats also recorded increases.

At Valterra, the recovery of Amandelbult following flooding in 2025 supported higher own-mined production, more than offsetting lower purchases of concentrate.

Valterra’s refined volumes also remained above underlying mined output for the fifth consecutive quarter as the company continued drawing down semi-finished inventory across its processing pipeline.

At Implats, improved processing availability enabled a further drawdown of excess semi-finished inventory, while Northam benefited from higher production at Booysendal and Eland as well as increased third-party purchases.

Elsewhere, Russia’s refined production fell 6% year-on-year to 148,000 ounces, while North American production is projected to decline 19% to 47,000 ounces, largely because of lower Canadian by-product output.

Against this backdrop, WPIC has maintained its 2026 global platinum supply outlook at 5.55 million ounces, broadly unchanged from its previous forecast.

Modest gains from South Africa are expected to be offset by declines elsewhere, leaving overall global supply broadly unchanged.

South Africa’s exceptionally strong first-half performance, which saw production rise 19% year-on-year, is expected to moderate in the second half as Valterra reschedules processing maintenance from the first half into the second half to mitigate the impact of higher winter electricity tariffs.

Zimbabwe, meanwhile, is expected to see its first-half production volatility ease as Zimplats moves beyond the furnace maintenance that affected output earlier in the year.

The country’s platinum industry will nevertheless remain exposed to operational and geological constraints, particularly declining grades and power reliability.

At the same time, demand outside the traditional automotive and jewellery markets is providing some support.

WPIC noted continued structural investment in artificial intelligence, data centres and advanced electronics, which is supporting selected industrial applications for platinum.

For Zimbabwe, the latest figures present a mixed picture: the country achieved a record quarterly refined output and remains an important contributor to global platinum supply, but its full-year production is still expected to decline as lower grades at Unki weigh on output.

The second-quarter performance also demonstrates how quickly production can be affected by smelter maintenance and power disruptions, with Zimplats’ furnace maintenance and Mimosa’s electricity challenges both featuring in the latest supply data.

With global supply forecast to remain broadly flat in 2026 and demand facing pressure from weaker automotive, jewellery and investment consumption, Zimbabwe’s ability to sustain production will increasingly depend on operational reliability, ore grades and the performance of its existing platinum assets.

Platinum market heads for H2 deficit after 548koz first-half surplus

0

The global platinum market is expected to swing back into deficit in the second half of 2026 as demand recovers and investment outflows ease, reversing a sizeable surplus accumulated during the first six months of the year, Mining Zimbabwe can report.

By Ryan Chigoche

The World Platinum Investment Council’s latest quarterly market review shows the market recorded a surplus of 244,000 ounces in the second quarter, taking the first-half surplus to 548,000 ounces.

That surplus is expected to give way to a 283,000-ounce deficit in the second half, as demand strengthens while supply remains broadly stable. The shift, however, will not be large enough to eliminate the surplus built up earlier in the year.

On current estimates, the 548,000-ounce first-half surplus would more than offset the projected 283,000-ounce second-half deficit, leaving the market with a full-year surplus of about 265,000 ounces. In other words, platinum is expected to move into deficit during the second half without ending 2026 in deficit overall.

The change in direction is largely tied to investment demand, which has emerged as the biggest swing factor in the 2026 market balance.

Investment demand reshapes the outlook

The council has reduced its estimate of expected investment demand by 601,000 ounces, a revision that has transformed its earlier forecast of a 297,000-ounce full-year deficit into the current 265,000-ounce surplus.

The downgrade followed a particularly weak second quarter for investment. Net investment recorded an outflow of 121,000 ounces, while exchange-traded fund holdings fell by 234,000 ounces. Bar and coin investment was also down 71% year-on-year.

The second-half outlook does not assume a sudden resurgence in investment demand. Instead, it anticipates that the heavy selling pressure will moderate, particularly from ETFs.

That distinction matters because investment flows can have a disproportionate effect on platinum’s relatively small market. A stabilisation in ETF holdings, alongside a recovery in physical investment, would remove a significant source of surplus and help tighten the market as other areas of demand recover.

The investment picture is also being shaped by a broader precious-metals environment in which prices have corrected from earlier highs amid changing expectations around interest rates, inflation and geopolitical risks.

While investment demand has weakened, however, underlying mine supply has remained comparatively resilient.

Supply growth remains limited

Global refined mine production rose 2% year-on-year to about 1.47 million ounces in the second quarter, with Zimbabwe and South Africa accounting for much of the increase.

South African refined production rose 4% to about 1.08 million ounces, helped by the recovery of Amandelbult following flooding in 2025, as well as higher output from Valterra Platinum, Northam and Implats.

Some of that increase, however, came from processing previously accumulated semi-finished material rather than a corresponding rise in underlying mined production. Valterra has continued drawing down inventories, while Implats has also processed stock accumulated earlier in the production cycle.

That distinction helps explain why strong first-half production has not translated into a major upgrade to the full-year supply outlook. South African production was 19% higher year-on-year in the first half, but the full-year increase is expected to be only about 1%.

Global 2026 supply has consequently been maintained at about 5.55 million ounces.

Higher platinum prices have improved mining economics and eased some margin pressure, prompting some previously deferred projects to restart or return to consideration. But those developments are not expected to deliver meaningful additional supply during 2026, leaving the market dependent on existing operations and recycling to meet demand.

Recycling is, in fact, expected to become an increasingly important source of supply.

Demand recovery faces a changing market

Recycled platinum supply is forecast to rise 8% this year to about 1.80 million ounces as higher prices encourage the processing of spent catalytic converters that were previously uneconomic to recover.

The increase comes as overall platinum demand remains under pressure. Total demand is forecast at about 7.09 million ounces in 2026, down 18% from the previous year, with jewellery demand expected to fall 15% to 1.88 million ounces and automotive demand declining 4% to 2.90 million ounces.

Industrial demand provides a more positive counterweight, rising 5% to about 2.39 million ounces.

Some of that growth is coming from newer applications that could become increasingly important over time. Demand for electrical applications is forecast to increase 19%, while glass demand is expected to rise 23%.

Platinum is also being used in high-end semiconductor manufacturing and in platinum-iridium crucibles used to produce crystals for optical interconnects in data centres. The applications are still relatively new, making their eventual contribution difficult to quantify, but they provide a potential source of incremental demand as investment in artificial intelligence and data-centre infrastructure expands.

At the same time, recycling is unlikely to provide an unlimited supply response. The council expects recycled supply could peak around 2027 or 2028, although volumes may continue rising before reaching that point.

Taken together, these trends leave the platinum market finely balanced beneath the headline full-year surplus.

A market caught between surplus and deficit

The latest outlook therefore points to a market moving in different directions over the course of 2026.

The first half was dominated by a substantial surplus, with weak investment demand and heavy ETF selling adding to available supply. In the second half, the expected easing of those outflows, combined with stronger demand and relatively limited supply growth, is projected to push the market into a 283,000-ounce deficit.

But because the first-half surplus is larger than the second-half shortfall, the market is still expected to finish the year with a 265,000-ounce surplus.

The balance will ultimately depend on whether investment selling eases as anticipated and whether the recovery in industrial and other demand materialises. Recycling and mine supply will provide additional counterweights, but neither is expected to deliver a dramatic increase in available platinum this year.

For now, the 2026 market is therefore not a story of an outright platinum shortage, but of a significant change in market balance from surplus in the first half to deficit in the second, with investment flows likely to determine how sharply that transition occurs.

Suspect Arrested Over US$12,000 Copper Cable Theft at Zimplats

0

A 20-year-old man has been arrested in connection with the alleged theft of armoured copper cables valued at US$12,000 from Zimplats Smelting Company in Selous, with police saying three other suspects remain at large.

The Zimbabwe Republic Police (ZRP) identified the suspect as Jairosi James Moyo (20) and said the theft occurred on 7 September 2026.

According to police, Moyo was allegedly part of a four-member group that targeted the copper cables at the platinum company’s smelting operation.

“The ZRP confirms the arrest of Jairosi James Moyo (20) in connection with a case of theft of armoured copper cables which occurred at Zimplats Smelting Company, Selous, on 07/09/26,” police said.

The three alleged accomplices fled and remain at large.

Police said investigations led officers to Makwiro Road in Selous, where Moyo was allegedly found removing the outer casings from the stolen cables.

“Following police investigations, the suspect was tracked and apprehended while removing the cable casings along Makwiro Road, Selous. The other three suspects fled the scene,” the ZRP said.

Officers recovered a 150mm x 91m, three-core armoured cable, together with a machete and a knife, from the suspect.

The recovered cable is believed to form part of the material allegedly stolen from the Zimplats facility.

The arrest highlights the continuing threat posed by copper cable theft to Zimbabwe’s mining and industrial infrastructure, where valuable electrical and armoured cables can become targets for criminal syndicates.

Police investigations are continuing as authorities work to identify and apprehend the three outstanding suspects.

Gold buying prices in Zimbabwe per gram/ ounce, 9 September 2026

0

Gold buying prices in Zimbabwe per gram/ ounce, 9 September 2026, from the official gold buyer and exporter, Fidelity Gold Refinery (FGR).

1 oz = 31.1035 g

CategoryUS$/gUS$/troy oz
SG 90% and above$131.88$4,101.93
SG 85% and above but below 90%$130.48$4,058.38
SG 80% and above but below 85%$129.09$4,015.15
SGF/SG 75% and above but below 80%$127.69$3,971.60
Sample 5g & above but below 10g$125.60$3,906.60
Fire Assay Cash$132.58$4,123.70


Note: The Fire Assay cash price applies to gold above 100g, with no sample deduction.

A sample of not more than 10g is deducted for the Fire Assay Transfer price.

#GoldPrices #GoldBuying #GoldMarket #GoldTrading #GoldRate #GoldPriceToday #GoldNews #PreciousMetals #GoldIndustry #GoldEconomy #FidelityGoldRefinery