Home Blog Page 55

Zimbabwe Bans Foreigners, foreign companies from the Small-Scale Gold Mining Sector with Immediate Effect

0

In a major policy shift, Zimbabwe has moved to reserve the country’s small-scale gold mining sector exclusively for local players after the Government announced an immediate ban on foreign participation in the segment, in what authorities describe as a move aimed at strengthening citizen empowerment, improving accountability, and formalising mining operations, Mining Zimbabwe can report.

By Ryan Chigoche

The new policy, announced by the Minister of Mines and Mining Development, Polite Kambamura, comes amid growing concern over unsustainable mining practices, escalating disputes involving foreign operators, and increasing pressure for Zimbabweans to derive greater benefit from the country’s mineral wealth.

According to the government, some foreign-linked operations within the small-scale mining sector have been associated with environmental degradation, weak regulatory compliance, and recurring conflicts involving local miners, farming communities, and surrounding residents.

Authorities have also expressed concern over the growing use of proxy ownership structures and partnership arrangements that effectively allow foreign interests to control activities reserved for local participants.

Against this backdrop, Kambamura announced that the new policy takes immediate effect and outlined the criteria that will now define Zimbabwe’s small and medium-scale gold mining sector.

“With immediate effect, the small-scale gold mining sector in Zimbabwe is reserved exclusively for Zimbabwean citizens and Zimbabwean citizen-wholly-owned entities,” said Kambamura.

“For purposes of this policy, no foreign individual, foreign-controlled company, or foreign beneficial owner shall be permitted to acquire, hold, or control any mining title classified under the small-scale gold mining category, participate directly or indirectly in the operation or management of small-scale gold mining activities, or enter into any arrangement intended to confer economic or operational control over small-scale gold mining activities reserved for Zimbabwean citizens,” Kambamura said.

Kambamura added that nominee arrangements, proxy ownership structures, undisclosed beneficial ownership arrangements, and any other mechanisms designed to circumvent the policy would be deemed unlawful and subject to cancellation and enforcement action in accordance with Zimbabwean law.

The Classification of Small-Scale Gold Mining Sector Reserved for Locals

Under the new framework, only Zimbabwean citizens and wholly Zimbabwean-owned entities will be permitted to own or operate small-scale gold mining ventures.

Government has classified small and medium-scale gold mining operations as projects producing up to 20 kilograms of gold per month and/or involving capital investment of up to US$15 million. Operations exceeding either threshold will instead fall under the large-scale mining framework, where foreign participation will continue to be allowed.

The move effectively creates a clearer distinction between the indigenous small-scale mining space and larger capital-intensive operations targeted at international investors.

Existing Operators Given Until 2027 to Regularise

In line with the new policy direction, Government has ordered all existing operators within the sector to regularise and re-register their mining titles with the Ministry of Mines and Mining Development before January 1, 2027.

The re-registration exercise will include verification of citizenship and beneficial ownership structures, disclosure of financing arrangements, and confirmation of compliance with environmental, labour, taxation, and mineral marketing regulations. Authorities will also assess production levels and investment thresholds to determine whether operations still qualify under the small-scale category.

Mining titles that fail to comply with the new framework risk cancellation or other regulatory action.

Meanwhile, foreign investors already operating in the small-scale gold sector have been directed to transition into the large-scale mining category by increasing production beyond 20 kilograms of gold per month and/or recapitalising investments above US$15 million before the 2027 deadline.

Despite the tighter restrictions in the small-scale sector, Government maintained that Zimbabwe remains open to responsible foreign investment in large-scale mining, exploration, beneficiation, infrastructure development, and value-addition projects.

Tougher Compliance Measures Introduced

Beyond ownership restrictions, the policy also introduces broader compliance measures aimed at strengthening oversight across the gold mining sector.

Mining companies will now be required to maintain transparent production and financial records while fully complying with environmental, taxation, royalty, labour, and safety obligations.

In one of the more far-reaching provisions, Government said senior and middle management positions across gold mines and other mining operations should now comprise 98 percent Zimbabwean nationals, with immediate compliance expected.

At the same time, authorities signalled plans to clamp down on idle mining assets held for speculative purposes, particularly those under foreign ownership, amid concerns that some claims are being retained without meaningful development.

As part of the push for improved sustainability and accountability, all mining projects will also be required to secure approved Environmental, Social and Governance (ESG) frameworks together with Environmental Impact Assessments (EIAs) before operations commence.

Government says the new measures are intended to support the growth and formalisation of indigenous mining enterprises, curb illicit mineral trade and fronting arrangements, improve mineral accountability, and ensure the country’s gold resources contribute more directly to national economic development under the National Development Strategy 2 framework.

The move also comes at a time when the Zimbabwe Miners Federation (ZMF) has repeatedly called for tighter regulation of foreign participation in the small-scale gold mining sector, arguing that uncontrolled foreign involvement was disadvantaging local miners and fuelling regulatory and operational challenges.
Freda Rebecca Hits 1 Million fatality free Shifts

0

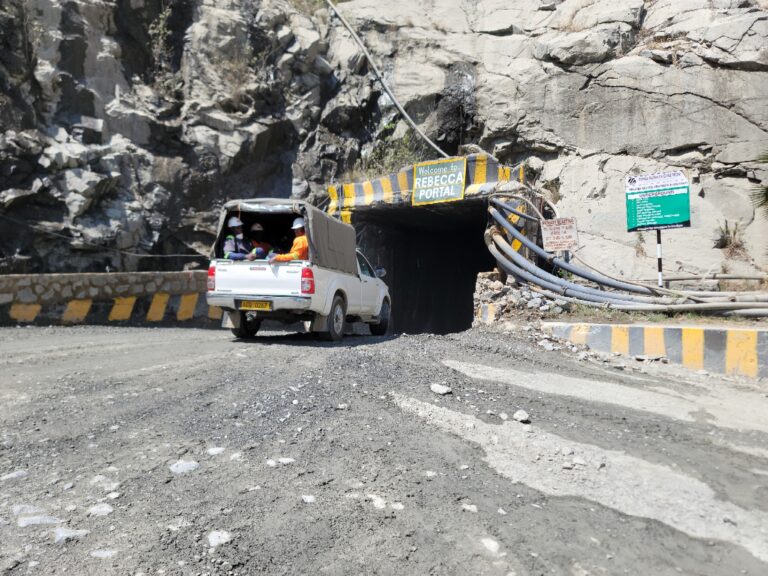
The country’s biggest gold miner, Freda Rebecca Gold Mine, a flagship asset of state-owned Mutapa Gold Resources, has achieved one million shifts without a single fatality, a milestone that underscores the operation’s deepening safety culture and operational discipline, Mining Zimbabwe can report.

By Rudairo Mapuranga

The mine celebrated the achievement this week, with General Manager Professor Wilfred Chinyere crediting a sustained transformation in engineering standards, risk assessment, and worker empowerment.

“When I first came to Freda, we had challenges, difficult underground conditions, limited flexibility, and a short life of mine,” Chinyere said in his welcome remarks. “But we said we need to correct this. We want to work in a comfortable environment where we can assure the safety of our people.”

Mutapa Gold Resources has allocated more than $12 million for exploration across its portfolio in 2026, with Freda Rebecca as a primary beneficiary. The goal is to extend the life of mine to 10 years per operation, up from the current four years.

“The next agenda is to accelerate this exploration programme, add more life to Freda, create good mining flexibility, and assure safety,” Chinyere said.

Record gold prices, which have exceeded $5,000 an ounce, are funding the push. “Because of the good gold price, we want to make mining more efficient and safer by investing a certain amount of money,” he added.

Beyond engineering and exploration, Chinyere has championed a cultural shift centred on giving every employee the confidence to stop unsafe work.

“We want to transform the culture of the way we are thinking so that we empower the worker,” he said. “When a worker’s empowerment is good, the worker should say ‘no’; the worker should come up with an idea where they say ‘no’.”

That philosophy, combined with deep risk assessment programmes, has been central to Freda Rebecca’s journey to one million fatality-free shifts.

Freda Rebecca produces gold as part of Mutapa Gold Resources, which also operates Shamva and Jena mines. The group currently averages 300 kilograms of gold per month and targets 570 kilograms as it extends mine lives and scales up safety systems.

“The value of the safety culture will go up,” Chinyere said. “We are in for a period where we transform the era we had.”

The one million shifts milestone positions Freda Rebecca as a safety benchmark in Zimbabwe’s gold mining sector and a testament to what disciplined investment, exploration, and worker empowerment can achieve.

Redwing Mine Restart Gains Momentum as Formal Operations Return to Historic Gold Asset

0

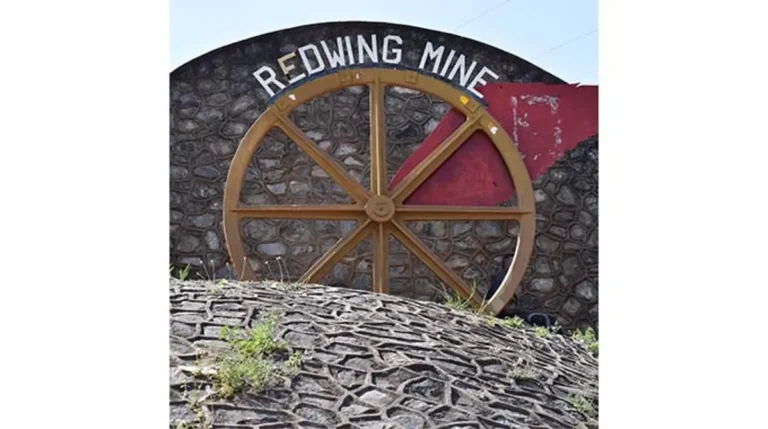
Redwing Mine is edging closer to a formal restart as dewatering operations continue to advance on schedule, with more than 544,000 cubic metres of water already pumped from the underground workings since January this year, Mining Zimbabwe can report.

By Ryan Chigoche

Parent company Namib Minerals said in its latest update that a cumulative total of approximately 544,570 cubic metres of water has been removed since dewatering commenced on 29 January 2026, with underground water levels receding by about 21.9 metres over the period.

It added that, as a result, combined pumping capacity currently stands at around 640 cubic metres per hour, while water levels have now fallen to approximately 74.9 metres below the Redwing Shaft surface collar, signalling continued progress toward the targeted underground access horizons.

Commenting on the progress in a statement, Namib Minerals Chief Executive Officer Tulani Sikwila said the company remained encouraged by the pace of the restart process.

“We are pleased that the restart process at Redwing is advancing on schedule,” said Sikwila.

“The progress we have made on dewatering reinforces our confidence in the restart pathway as we look ahead to the next phase of technical work at the mine. Redwing is a central component of our long-term strategy of building a scaled, multi-asset African gold platform through disciplined brownfield development and phased capital deployment,” he said.

Dewatering is considered a critical stage in the revival of underground mines, allowing operators to regain access to flooded workings for inspections, rehabilitation, and eventual mining operations.

Located near Penhalonga in Manicaland Province, Redwing is one of Zimbabwe’s historic gold mines and has previously produced about 650,000 ounces of gold. The mine currently hosts an estimated 1.18 million ounces of gold in measured and indicated resources, according to the company.

In recent years, however, the mine became largely associated with widespread artisanal and small-scale mining activities following prolonged operational disruptions and financial challenges. Informal mining operations became dominant across parts of the concession, with the area frequently drawing attention over unsafe mining practices, environmental degradation, and fatal accidents linked to unregulated underground workings.

The planned restart by Namib Minerals is expected to mark a shift toward formalised large-scale operations at the mine, as the company moves to rehabilitate infrastructure and restore structured underground production at the historic asset.

Namib said high-capacity submersible pumps are expected on site within the coming week to further increase pumping capacity, while the dewatering infrastructure has continued operating without major interruptions since the process began earlier this year.

The restart also comes as Zimbabwe seeks to expand gold production and strengthen mineral export earnings, with gold remaining one of the country’s leading sources of foreign currency alongside platinum group metals and lithium.

Once targeted dewatering levels are achieved, the company is expected to proceed with underground inspections, technical assessments, and rehabilitation work ahead of broader restart activities.

The ongoing dewatering at Redwing Mine forms part of Namib Minerals’ broader US$300 million to US$400 million capital programme across its three Zimbabwean gold assets, including Redwing, Mazowe, and How Mine, aimed at restoring and expanding production through phased redevelopment and brownfield investment.

Mnangagwa to Commission 10MW Kwekwe Solar Plant as Zimbabwe Pushes for Energy Independence

0

President Emmerson Mnangagwa will on Friday launch the first phase of the New Glovers Solar Project, a 10-megawatt plant near Munyati Power Station in Kwekwe, as Zimbabwe pushes to cut power imports and ease pressure on foreign currency reserves, Mining Zimbabwe can report.

By Rudairo Mapuranga

The US$20-million facility (estimated based on regional benchmarks), built by the Public Service Pension Fund (PSPF), comprises 18,600 solar panels, 31 inverters, and two smart transformers. A 6-kilometre transmission line connects it directly to the national grid. Annual output is forecast at roughly 20 gigawatt-hours, enough to power about 9,000 average Zimbabwean households.

The 10MW phase is the first step toward a total installed capacity of 110MW once the project is fully completed. No timeline for the remaining 100MW was given in the advisory.

“The plant will significantly reduce reliance on energy imports, conserve foreign currency, and promote energy independence,” the Public Service Commission said in a media advisory.

Zimbabwe currently imports up to 400MW from South Africa’s Eskom and Mozambique’s HCB to cover chronic generation shortfalls at Hwange and Kariba.

The launch event is scheduled for 08:00 on 22 May at the New Glovers Solar Park in Chief Samambwa’s area, Kwekwe District, Midlands Province.

For Zimbabwe’s mining sector, which consumes more than half of the country’s electricity, the project offers a template for pension fund-backed independent power production. The PSPF did not disclose the project’s tariff or power purchase agreement terms.

Zimbabwe Steel Boom Faces South Africa Tariff Barrier as Manhize Exports Surge

0

When Dinson Iron and Steel Company (Disco) fired up its US$1.5 billion Manhize plant in 2024, Zimbabwe finally broke free from spending half a billion dollars annually on imported steel. By the first quarter of 2026, steel export earnings had rocketed 254% to US$68.22 million, with regional buyers scrambling for Zimbabwean billets, rebars, and wire rods, particularly in South Africa, where the once-dominant steel industry is in freefall, Mining Zimbabwe can report.

By Rudairo Mapuranga

But just as Zimbabwean steel begins to reshape regional trade, a protectionist offensive from Pretoria threatens to slam the door shut. On 15 May 2026, South Africa gazetted sweeping new import duties on steel and downstream metal products, ranging from 10% to 30%. The official justification is to shield South Africa’s struggling industry from “low-cost imports.” The practical effect, however, is a one-sided recalibration of the bilateral trade relationship that has long favoured South Africa and has now become palpably unfair to Zimbabwe.

The Surge That Shook the Region

Zimbabwe’s steel resurgence is anything but ordinary. In 2025 alone, steel export earnings surged 450% to US$92.1 million from 146,314 tonnes, transforming a perennial net importer into a regional powerhouse at the very moment ArcelorMittal South Africa posted a headline loss of 3.355 billion rand (US$207.86 million) and shut down its long-steel plants. Into that vacuum stepped Zimbabwe. Primary steel imports into South Africa reached a record 1.56 million tonnes in 2025, with semi-finished products such as billets and blooms leaping by over 514%.

The quality and reliability of Disco’s output have drawn “quite exciting” feedback from regional buyers, while 98% of its raw materials—coke, limestone, and iron ore—are sourced locally. That is genuine value addition, the kind that industrial policy is supposed to reward. Yet, at the very moment Zimbabwe should be reaping the benefits of its long-overdue industrial awakening, South Africa has erected a new tariff barrier.

The Irony of Protectionism

The May 2026 duties apply to a broad range of products: 10% on flat-rolled and alloy steels, 15% on tubes and pipes, 20% on hand tools, and 30% on select fittings and washers. Rebates are available only for products “not available locally,” subject to permits from the International Trade Administration Commission, whose guidelines remain unpublished. For Zimbabwean exporters who have fought to build reliable supply chains, this creates immediate legal uncertainty.

Pretoria’s action follows a pattern. In March 2026, South Africa imposed duties of 74.98% on Chinese steel and 20.32% on Thai steel after a two-year dumping probe. While those measures explicitly target China and Thailand, the broader tariff review comes at a moment when Zimbabwe has become the most dynamic new steel supplier in the region. The message is unmistakable: South Africa will protect its domestic industry even if that means chilling competition from its closest neighbour.

A Trade Imbalance That Has Lasted Too Long

The steel dispute is only the most visible symptom of a relationship that has long been tilted in South Africa’s favour. In 2025, Zimbabwe exported goods worth approximately US$526 million to South Africa. During the same period, South Africa exported a staggering US$4.3 billion worth of goods to Zimbabwe. That is an eightfold imbalance, with Pretoria enjoying a trade surplus of nearly US$3.8 billion.

The composition of those imports is even more telling. South Africa ships to Zimbabwe not only mining equipment and machinery, which accounted for US$508 million in 2025, but also US$417.8 million in cereals, US$337.6 million in vehicles, and US$221.1 million in plastics. Many of these goods, from foodstuffs to basic manufactured products, could be produced locally if Zimbabwe’s own industries were given a fair chance. Yet under the SADC Free Trade Area framework, Zimbabwe has largely kept its market open to South African goods, while South Africa now deploys the very tariff tools it has long discouraged Zimbabwe from using.

As early as 1992, South Africa raised tariffs on many Zimbabwean goods, causing industry closures and job losses. That pattern has continued. Even when Zimbabwe qualifies for preferential access, the non-tariff barriers, port delays, standards certification, and border red tape remain formidable. Meanwhile, Zimbabwe’s own mining sector spends roughly US$2.1 billion annually on imported machinery, equipment, and services, the overwhelming majority sourced from South Africa. An Afreximbank report found that 80% of Zimbabwe’s intra-African mining-related imports, totalling US$4.7 billion, come from South Africa.

What Fairness Would Require

South Africa cannot have it both ways. It cannot demand open access for its own exports—machinery, vehicles, plastics, food, chemicals, and consumer goods—while simultaneously closing its market to Zimbabwe’s emerging manufactured goods. If the SADC Free Trade Area means anything, it means reciprocal market opening, not one-way liberalisation masked by protectionist fine print.

Zimbabwe has already begun taking modest corrective steps. In 2025, Zimbabwe reduced imports from South Africa by US$140 million as local industry rebounded. The Local Content Strategy, approved in 2019, aims to raise local content levels from 25% to 80% and boost manufacturing capacity utilisation from 45% to 75%. But these measures remain inadequate against a partner that deploys anti-dumping duties, safeguard tariffs, and rebate permits with surgical precision.

If South Africa is serious about regional integration, it must offer Zimbabwe reciprocal treatment: genuine duty-free access for Zimbabwean manufactured goods, transparent rebate procedures, and an end to the non-tariff barriers that have long choked Zimbabwean exports. Until that happens, Zimbabwe would be well within its rights to re-examine its own import regime, particularly for goods that compete directly with domestic industry.

Zimbabwe’s steel resurgence is a hard-won achievement. The Manhize plant now employs over 2,000 workers directly, a figure projected to reach 25,000 at full capacity, and is expected to contribute US$5 billion annually to the national economy. That transformation should be celebrated, not obstructed by a neighbour that benefits enormously from an open Zimbabwean market while raising walls against Zimbabwean goods.

Pretoria’s new steel duties are, in effect, a “ban without saying it.” They are a reminder that trade relationships are not fair by default—they are fair when both sides have the courage to enforce reciprocity. Zimbabwe has made its move. It is time for South Africa to match it.

Gold buying prices in Zimbabwe per gram/ ounce, 21 May 2026

0

Gold buying prices in Zimbabwe per gram/ ounce, 21 May 2026, from the official gold buyer and exporter Fidelity Gold Refinery (FGR).

1 oz = 31.1035 g

CategoryPrice ($/g)Price ($/oz)
SG 90% and above135.884,226.52
SG 85% but less than 90%134.454,182.05
SG 80% but less than 85%133.014,137.27
SG 75% but less than 80%131.574,092.48
Sample (5–10g)129.414,025.30
Fire Assay CASH136.604,248.92


Note: The Fire Assay cash price applies to gold above 100g, with no sample deduction.

A sample of not more than 10g is deducted for the Fire Assay Transfer price.


#GoldPrices #GoldBuying #GoldMarket #GoldTrading #GoldRate #GoldPriceToday #GoldNews #PreciousMetals #GoldIndustry #GoldEconomy #FidelityGoldRefinery

Premier’s Endless Nightmare: 1.18 Billion More Shares Gone, No Revenue, No Production

0

Premier African Minerals Ltd. has issued another 1.18 billion shares to settle just £217,000 of creditor bills and unpaid salaries, pushing its total share count to 39.3 billion as the Zulu Lithium project remains years away from generating any revenue, Mining Zimbabwe can report.

By Rudairo Mapuranga

The London-listed miner printed 881.7 million shares to pay trade creditors and 295.8 million shares to clear accrued but unpaid salaries owed to former directors and consultants, according to a statement released today. The shares were issued at 0.0185 pence each, the same price as the company’s last placing on May 13.

Six months ago, Premier had about 9.35 billion shares outstanding. Today, it has 39.3 billion. That is more than a fourfold increase in the space of half a year, accomplished through a relentless series of equity fundraises, interest conversions, and creditor settlements. Not one of those transactions has been accompanied by a single pound of revenue from spodumene concentrate sales.

The company’s market capitalisation, based on today’s issue price, is approximately £7.3 million, spread across nearly 40 billion shares. Each share is now worth a fraction of a penny, and the market has long since priced in what Premier’s upbeat press releases will not admit: the project has destroyed shareholder value on a scale that makes recovery all but impossible.

Operationally, Premier says the new Xinhai flotation plant at Zulu has completed most cold commissioning activities using water and is preparing to introduce ore. Hot commissioning is still targeted for the second quarter of 2026, which ends in five weeks. Even if that deadline is met, Zimbabwe’s government suspended lithium concentrate exports months ago, and Premier has not secured a firm exemption, only stating that it remains “in dialogue” with the Ministry of Mines.

Managing Director Graham Hill said in the statement that the company is pleased with progress, but the financial reality contradicts the optimism. Each new share issuance transfers ownership from existing holders to new entrants at fire-sale prices, and the latest 1.18 billion shares were issued simply to clear debts that would barely buy a modest house in London.

Premier may eventually commission the flotation plant and produce spodumene concentrate. But with nearly 40 billion shares already in issue, and more dilution almost certain if commissioning slips again, the question for shareholders is no longer whether Zulu can work. It is whether there will be any equity left worth owning by the time it does.

Gold buying prices in Zimbabwe per gram/ ounce, 20 May 2026

Gold buying prices in Zimbabwe per gram/ ounce, 20 May 2026, from the official gold buyer and exporter Fidelity Gold Refinery (FGR).

1 oz = 31.1035 g

CategoryPrice ($/g)Price ($/oz)
SG 90% and above133.934,165.69
SG 85% but less than 90%132.514,121.52
SG 80% but less than 85%131.094,077.36
SG 75% but less than 80%129.674,033.19
Sample (5–10g)127.553,967.25
Fire Assay CASH134.634,187.46


Note: The Fire Assay cash price applies to gold above 100g, with no sample deduction.

A sample of not more than 10g is deducted for the Fire Assay Transfer price.


#GoldPrices #GoldBuying #GoldMarket #GoldTrading #GoldRate #GoldPriceToday #GoldNews #PreciousMetals #GoldIndustry #GoldEconomy #FidelityGoldRefinery

Beneficiation Push Reshapes Lithium Sector, Edging Out Small-Scale Miners

0

Artisanal and small-scale mining (ASM) activity in Zimbabwe’s lithium sector is being steadily pushed out as tightening export restrictions and a shift toward high-value processing redraw the structure of the industry, Mining Zimbabwe can report.

By Ryan Chigoche

Recent policy developments, including the ban on lithium concentrates and the broader push to transition toward lithium sulphate production by 2027, are raising the minimum threshold for participation in the sector. In effect, only large-scale, capitalised miners with processing capacity are now positioned to operate viably within the formal market.

For ASM operators, this marks a breaking point.

Most small-scale miners lack the infrastructure to beneficiate lithium ore beyond basic extraction. With export channels for raw and semi-processed material effectively closed, and no widespread access to local processing facilities, their route to market has largely disappeared.

What was once a low-barrier entry point into the lithium value chain is now becoming a highly controlled, capital-intensive industry.

This structural shift is unfolding against the backdrop of weakening global lithium prices, which have further squeezed already thin margins at the ASM level. Even where informal trading persists, lower prices are reducing incentives to continue production, reinforcing the slowdown.

The result is increasingly visible on the ground: idle pits, thinning mining clusters, and growing piles of unsold lithium ore.

These trends were already beginning to take shape prior to the latest policy tightening. A recent field-based assessment by the Zimbabwe Environmental Law Organisation (ZELO), which covered Goromonzi, Mberengwa, Mutoko, and Insiza, documented a noticeable decline in ASM activity, with many sites either abandoned or operating intermittently.

“The reduction in ASM activity is attributed to several factors, including the forced removal of miners, the ban on the export of unbeneficiated lithium, and the sharp decline in global lithium prices. These developments have had a disproportionate impact on small-scale miners, who lack the capacity to process lithium ore independently,” ZELO noted in its Mines to Market report just before the ban.

What has changed since that assessment is the pace and direction of policy enforcement.

The move to restrict lithium concentrate exports, effectively fast-tracking a beneficiation agenda initially targeted for 2027, has deepened the exclusion of ASM miners from formal markets.

While the policy is designed to anchor value addition within Zimbabwe, its immediate effect has been to concentrate participation among large producers able to invest in processing plants and downstream integration.

In key ASM districts such as Mutoko and Goromonzi, previously active mining sites are increasingly falling silent. Similar patterns are emerging in Mberengwa and Insiza, where informal operations have thinned out significantly. What began as a slowdown is now hardening into a broader exit of small-scale players from the lithium space.

This points to a deeper transformation of Zimbabwe’s lithium sector.

Rather than a temporary downturn driven by prices, the industry is undergoing a structural consolidation. Participation is shifting away from dispersed, labour-intensive ASM operations toward a smaller number of vertically integrated producers aligned with the country’s beneficiation strategy.

Without deliberate mechanisms to integrate ASM, such as shared processing facilities, toll treatment arrangements, or formalised buying frameworks, the current trajectory suggests that small-scale miners will remain locked out.

On the ground, the evidence is already clear: ASM activity is not just declining; it is being phased out of Zimbabwe’s lithium value chain.

Zimbabwe ASM Gold Deliveries Jump 20.7% in April as 50-Tonne Target Remains Within Reach

0
  • Artisanal deliveries reached 2,110 kg in April from 1,748 kg in March, offsetting a softer year-on-year comparison. The first four months of 2026 are tracking ahead of 2025, keeping the 50-tonne annual target firmly within reach.

Gold deliveries to Fidelity Gold Refinery (FGR) rebounded strongly in April 2026, driven by a sharp recovery in artisanal and small-scale mining (ASM) output. Total deliveries for the month reached 3,324.5926 kg, up 16.5% from March 2026’s 2,854.0030 kg, according to official FGR statistics obtained by Mining Zimbabwe.

By Rudairo Mapuranga

The ASM sector, which now accounts for roughly 75% of national gold output, led the resurgence. ASM deliveries in April 2026 stood at 2,110.6550 kg, a 20.7% increase from March 2026’s 1,748.6953 kg. Large-scale miners also recorded gains, delivering 1,213.9376 kg in April, up 9.8% from 1,105.3077 kg in March.

The month-on-month recovery is particularly significant following a subdued March, which industry sources attributed to temporary policy uncertainty and the lingering effects of a wet season that had constrained access to some alluvial and shallow mining areas.

While the month-on-month performance is encouraging, year-on-year comparisons show a slight decline. Total April 2025 deliveries were 3,542.1734 kg, meaning April 2026’s total of 3,324.5926 kg represents a 6.1% decrease from the same month last year.

The decline is entirely attributable to the ASM segment. ASM deliveries in April 2025 were 2,926.1086 kg, compared to 2,110.6550 kg in April 2026, a 27.9% drop. Large-scale miners, however, improved year on year, delivering 1,213.9376 kg in April 2026 versus 990.0748 kg in April 2025, a 22.6% increase.

The contrasting trajectories reflect two ongoing structural trends: large-scale production is steadily recovering following years of underinvestment, while ASM output is becoming more volatile as formalisation efforts and enforcement against smuggling create temporary disruptions before a more stable, fully documented production base emerges.

First Four Months: 2026 Edges Ahead of 2025

Crucially, the cumulative performance for the first four months of 2026 remains ahead of the same period in 2025, keeping Zimbabwe’s ambitious 50-tonne annual target well within reach.

The 2026 cumulative figure of 12,636.5166 kg represents a 1.3% increase over 2025’s 12,471.6279 kg for the same four-month period. While modest, this margin is expected to widen as new ASM formalisation programmes, expanded buying centres, and the reopening of large-scale mines gain momentum through the drier winter months, when mining activity typically accelerates.

50-Tonne Target Within Reach

Zimbabwe’s gold sector delivered a record 46.7 tonnes in 2025. For 2026, FGR and the government have set a target of 50 tonnes, a 7% increase. The first four months’ performance suggests this target is achievable, though execution will need to tighten.

A simple annualisation of the January to April 2026 run rate (12,636.5 kg × 3) yields 37.9 tonnes, which would fall short of 50 tonnes. However, historical production patterns show that the second and third quarters, May through September, consistently deliver higher volumes than the first four months, as drier conditions and post-harvest labour availability boost ASM activity.

To reach 50 tonnes, Zimbabwe needs average monthly deliveries of approximately 4,167 kg for the remaining eight months of 2026 (May–December). That is 25% higher than April’s 3,325 kg, but well within historical peak performance levels. In 2025, monthly deliveries exceeded 4,000 kg in July (4,067 kg), August (4,134 kg), and September (4,254 kg). With new capacity coming online, including the phased reopening of Mazowe and Redwing mines under Namib Minerals, and expanded ASM formalisation at Elvington and Amaveni, surpassing 4,000 kg per month in the second half of 2026 is entirely plausible.

FGR’s own projections, based on mine-level production schedules and ASM registration data, remain optimistic. The Gold Development Initiative Fund (GDIF) and the newly established Gold Trade Enforcement Unit (GTEU) are also expected to reduce leakage to parallel markets, further boosting official deliveries.

ASM Formalisation: Short-Term Pain, Long-Term Gain

The 27.9% year-on-year decline in April ASM deliveries should be interpreted with caution. It does not necessarily mean less gold is being mined; rather, it may reflect a temporary contraction in officially delivered gold as enforcement against smuggling intensifies and as the digital Gold Card registration system rolls out.

Zimbabwe Miners Federation President Henrietta Rushwaya has consistently argued that formalisation creates a short-term dip in reported output as previously informal miners adjust to new compliance requirements, before a sustained increase as financing, equipment, and technical support reach registered operators.

The 20.7% month-on-month ASM rebound from March to April supports this interpretation. March’s low of 1,748 kg appears to have been an anomaly, and April’s 2,110 kg, while still below April 2025, shows the sector’s underlying resilience.

Large-Scale Mining: The Quiet Recovery

While ASM dominates headlines, large-scale mining is quietly rebuilding. April 2026’s 1,213.9 kg from large-scale operators was the highest monthly figure since at least early 2025, and the 22.6% year-on-year increase confirms that capital investment is translating into output.

Key contributors include:

  • Mutapa Gold’s Freda Rebecca mine, which achieved a record 240 kg in March and is on track for similar or better performance in subsequent months.
  • RioZim’s Renco Mine is back online and contributing consistently following its successful capital restructuring.
  • Caledonia Mining Corporation’s Blanket Mine, which, despite below-guidance Q1 output due to policy headwinds, remains a steady producer, with expansion plans at Bilboes progressing.

As Namib Minerals brings Mazowe and Redwing back into production, a process expected to accelerate through the second half of 2026, large-scale output could reach 1,500–1,800 kg per month by year-end.

Outlook: Second Half Acceleration

The gold sector’s performance in April 2026 sends a clear signal: the production boom is intact. Month-on-month growth of 16.5% in total deliveries and 20.7% in ASM deliveries demonstrates that March’s softness was temporary, not structural.

With 12.64 tonnes already delivered in the first four months, slightly ahead of last year’s record pace, and with the dry season, expanded formalisation, and new large-scale capacity all pointing to a stronger second half, the 50-tonne target for 2026 remains firmly within reach.

For context, the remaining eight months of 2026 would need to deliver 37.36 tonnes to hit 50 tonnes. That is an average of 4,670 kg per month, a significant lift from April’s 3,325 kg, but one that has been achieved before. In the final four months of 2025 (September–December), Zimbabwe averaged 4,350 kg per month. A modest 7% improvement on that already achieved run rate would deliver the target.

The margin for error is narrow, but the direction of travel is clear: gold production is rising, formalisation is deepening, and investment is flowing. Zimbabwe’s gold dominance is not a mirage; it is being built, month by month, kilogram by kilogram.